
- Part 1: The Mechanics of Debt Consolidation
- The Mathematical Advantage
- Part 2: Debt Consolidation vs. Debt Relief (Settlement)
- Part 3: The Dangerous Behavioral Trap: “Reloading”
- Part 4: Side-by-Side: US vs. UK Consolidation Localization
- Part 5: Step-by-Step Strategic Roadmap for Consolidation Success
- Step 1: Conduct a Comprehensive Overhead Audit
- Step 2: Establish Your Starter Buffer
- Step 3: Implement Spend Friction
- Step 4: Automate Your Installments
- Step 5: Allocate Windfalls to Prepay the Principal
- Part 6: Standard AdSense & E-E-A-T Compliance Framework
- What to Do Next
Juggling multiple monthly credit card payments is one of the most mentally exhausting experiences in personal finance. Between tracking different due dates, managing minimum payment calculations, and watching high interest rates swallow up your hard-earned cash, it is incredibly easy to lose hope [158]. You feel like you are running on a financial treadmill, working harder every day just to stay in the exact same spot [158, 180].
In this environment of perpetual stress, the promise of a debt consolidation loan sounds like a magic wand, offering specialized debt consolidation personal loans to clear your card balances. Advertisements promise to combine all your messy credit cards into a single, simple monthly payment with a much lower interest rate.
But is consolidation actually saving you money, or is it simply moving deck chairs on a sinking ship? While debt consolidation personal loans can be incredibly powerful financial accelerators, they come with a massive psychological warning label. If you do not address the behavioral spending habits that caused the debt in the first place, consolidation can actually double what you owe. In this comprehensive guide, we will evaluate the mathematical rules of consolidation, weigh the structural pros and cons of debt consolidation personal loans, explore regional US and UK differences, and show you exactly how to execute this strategy safely.
Part 1: The Mechanics of Debt Consolidation
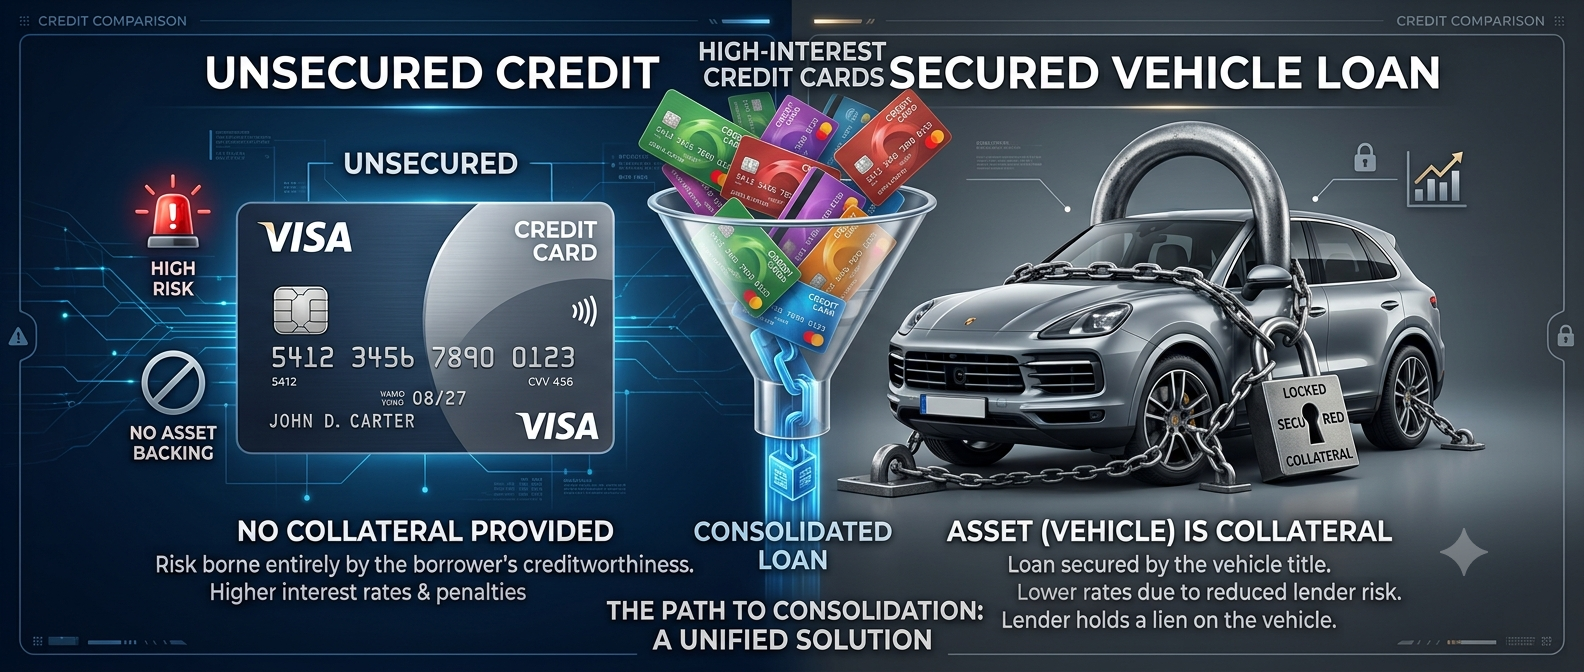
To determine if a consolidation loan is the right choice for your budget, you must first understand how these loans operate [183]. Debt consolidation is the process of combining multiple separate debts into a single, brand-new installment personal loan, which is why debt consolidation personal loans require strong repayment discipline [183].
Here is how the structural transaction works:
- The New Capital: You apply for a fixed-rate personal installment loan equal to the sum of your outstanding credit card balances.
- The Wiped Slate: Once approved, the lender sends the loan funds directly to your bank account, or they use the capital to pay off your credit card accounts directly, reducing their balances to exactly zero [183].
- The Structured Finish Line: Your credit cards are now empty, and you are left with a single monthly payment on the new installment loan. Because installment loans have a fixed repayment term (usually 2 to 5 years) and a fixed interest rate, you have a guaranteed date on which you will be completely debt-free.
                      THE CONSOLIDATION FUNNEL

        +----------+  +----------+  +----------+  +----------+
        | Card A   |  | Card B   |  | Store C  |  | Loan D   |
        | 24% APR  |  | 21% APR  |  | 28% APR  |  | 18% APR  |
        +----------+  +----------+  +----------+  +----------+
              |             |             |             |
              v             v             v             v
        +----------------------------------------------------+
        |             CONSOLIDATION PERSONAL LOAN            |
        |                 Fixed 10% APR / Term               |
        +----------------------------------------------------+
                                |
                                v
        +----------------------------------------------------+
        |      Single, Lower, Structured Monthly Payment     |
        +----------------------------------------------------+
The Mathematical Advantage
Let us compare the numbers of a typical consolidation scenario to see how much money can be saved:
Imagine you have $10,000 in outstanding debt split across three revolving credit cards with a weighted average interest rate of 24% APR. Your monthly minimum payments total $300. If you continue only paying the minimums, it will take you over 20 years to clear the balances, and you will pay more than $15,000 in interest alone!
Now, suppose you qualify for a $10,000 debt consolidation personal loan at a fixed interest rate of 10% APR over a 3-year term:
- Your New Monthly Payment: ~$322
- Your Total Payoff Time: Exactly 36 months (3 years)
- Your Total Interest Paid: ~$1,600
- Your Total Savings: Over $13,400 in interest and 17 years of your life!
While your monthly cash commitment went up slightly (from $300 to $322), 100% of your payment is structured to guarantee a $0 balance in 3 years. This is the ultimate power of combining payments when the math aligns [183].
Part 2: Debt Consolidation vs. Debt Relief (Settlement)
A common point of confusion is mixing up debt consolidation personal loans with debt relief or debt settlement programs [183]. These are completely different financial strategies with vastly different impacts on your net worth and credit profile [184]:
| Focus Metric | Debt Consolidation Loan | Debt Relief (Settlement) |
|---|---|---|
| Principal Owed | You pay back 100% of what you borrowed [183, 184] | You negotiate to pay 50% to 70% of the principal [183, 184] |
| Credit Rating Impact | Minimal to Positive (Utilization plummets; score rises) [184, 188] | Catastrophic Drop (Requires delinquency before settling) [184, 188] |
| Approval Qualification | Requires a decent credit score to get a competitive rate [184] | Based on real financial hardship and default status [184, 187] |
| Monetization Cost | Small origination fee; monthly interest [183] | 15% to 25% of settled debt paid as a negotiator fee [190] |
| Tax Implications | None (No debt is forgiven) | Forgiven debt over $600 is treated as taxable income [189] |
Part 3: The Dangerous Behavioral Trap: “Reloading”
If consolidation is so mathematically superior, why do so many financial counselors warn against it? The answer lies in human psychology and behavioral finance.
When you consolidate your debts, you are using a new loan to wipe your credit card balances down to $0.00. For many consumers, seeing those empty limits triggers a dangerous psychological release. They tell themselves, “I have cleared my credit cards, my debt problem is solved!”
However, because they did not fix the behavioral spending habits that caused the debt in the first place, they continue using those cards for lifestyle purchases [221, 223]. Over the next 12 to 24 months, they slowly run up those balances again. This is known in the underwriting industry as the reloading trap, which is the biggest psychological risk associated with debt consolidation personal loans—the catastrophic situation where you now owe the full consolidation loan payment plus a whole new set of maxed-out credit cards [221, 222].
To execute a consolidation strategy safely, you must pair the new loan with strict behavioral safeguards. You must freeze, cut up, or lock away your empty credit cards so they can never be used for impulse spending again [223].
Part 4: Side-by-Side: US vs. UK Consolidation Localization
Consolidation loan options, banking structures, and financial regulations differ depending on whether you live in the United States or the United Kingdom. Use this reference table to guide your search for options in your region:
| Feature Focus | 🇺🇸 United States Version | 🇬🇧 United Kingdom Version |
|---|---|---|
| Primary Providers | National banks, credit unions, specialized online lenders (e.g., SoFi, Upstart, Best Egg) | High-street banks, building societies, peer-to-peer lenders (e.g., Zopa, Admiral) |
| Typical Term Structures | 2 to 7 years (24 to 84 months) | 1 to 5 years (12 to 60 months) |
| Primary Credit Score Impact | repayment of debt consolidation personal loans (FICO / VantageScore and other bureaus (reported to Experian, Equifax, TransUnion) | Equifax / Experian / TransUnion UK Statutory Credit Rating |
| Prepayment Penalties | Prohibited by federal law on most standard consumer personal loans. | Standard variable loans allow penalty-free payoff; some fixed loans may charge up to 58 days of interest. |
| Collateral Alternative | Home Equity Loans or HELOCs (high risk) | Secured Personal Loans or Homeowner Loans (extremely high risk) |
Part 5: Step-by-Step Strategic Roadmap for Consolidation Success
To ensure your consolidation loan is a success, follow this precise execution roadmap:
Step 1: Conduct a Comprehensive Overhead Audit
Before applying for any loan, you must verify that your monthly cash flow can comfortably absorb the new payment. Download your past three months of transaction history and perform a 90-day bank statement audit to identify and eliminate any wasteful, variable cash leaks [224]. Map out your fixed vs. variable overhead survival budget so you know exactly how much cash is available for the installment payment.
Step 2: Establish Your Starter Buffer
Do not consolidate until you have established a basic cash reserve [227]. If you do not have a starter emergency savings buffer sitting in a separate account, the very next minor emergency will force you to swipe your credit cards again, immediately triggering the reloading trap, which is the biggest psychological risk associated with debt consolidation personal loans [175, 225].
Step 3: Implement Spend Friction
The second your consolidation loan is approved and your credit card balances are wiped to $0.00, introduce mandatory friction. Implement the 48-Hour Spend Pause for any purchase over $50 to prevent impulse buying loops [223]. Lock your physical cards in a safe or a block of ice to ensure they remain empty [223].
Step 4: Automate Your Installments
Set up automatic payday withdrawals for your new consolidation loan [173, 225]. On-time payment history is the single largest component of your credit rating, so automating this payment ensures your score steadily climbs month after month [173, 221].
Step 5: Allocate Windfalls to Prepay the Principal
If you receive an annual bonus, tax refund, or need to decide what to do with tax refund money, direct those windfalls straight to the principal of your consolidation loan [173]. Because personal loans are simple-interest contracts, prepaying the principal reduces the total interest you will pay and cuts months off your term.
Part 6: Standard AdSense & E-E-A-T Compliance Framework
At DebtPave, our priority is honest, evidence-based personal finance education. A debt consolidation personal loan is not a cure for debt; it is simply a tool to restructure your existing liabilities [183]. Wiping card balances to zero does not improve your net worth; only paying down the principal of your debt increases your wealth [161].
If your credit score is too low to qualify for a competitive interest rate (below 12% APR), do not apply for a high-interest consolidation loan, which will simply compound your interest costs. Instead, focus on using the Debt Snowball or Avalanche method to clear smaller accounts first while rebuilding your score [226].
What to Do Next
Gather your current statements and calculate your weighted average interest rate. If your credit cards are charging 22%+ APR and you can qualify for an installment loan at 10% APR, consolidation is a highly logical financial move [183]. Protect your balances from reloading by locking away your cards, automate your new installment payment on payday, and use your freed-up cash flow to build your long-term wealth [158, 225].
Disclosure: This post contains affiliate links. If you click through and sign up for a recommended product, we may earn a small commission at no extra cost to you. We only recommend products we verify and trust [173].
Disclaimer: DebtPave provides free, educational personal finance resources to help you take control of your cash flow. We are not certified financial advisors or legal experts. Always consult with a registered professional before making major financial decisions [173].